How Recent Interest Rate Increases Could Impact Connecticut’s Fall Real Estate Market
If you were hoping interest rates would finally give homebuyers a break this fall, the latest news probably wasn't what you wanted to hear.
The Federal Reserve raised its benchmark interest rate by 0.25 percentage points at its September 2026 meeting, bringing the federal funds target range to 3.75%–4.00%.
And mortgage rates have been moving higher, too.
As of September 24, the average 30-year fixed mortgage rate reached 7.03%, up from 6.95% the previous week and 6.30% a year ago, according to Freddie Mac.
So what does that actually mean for Connecticut's fall real estate market?
Probably not what you think.
1. Buyers Are Going to Feel the Payment More Than Ever
The biggest immediate impact is affordability.
When mortgage rates rise, buyers don't necessarily stop wanting a home. They may simply have to adjust what they can comfortably afford.
For example, a buyer who was comfortable shopping at a certain price point when rates were lower may now find that the same purchase comes with a noticeably higher monthly payment.
And that's happening at the same time Connecticut home prices remain elevated.
Connecticut buyers are already dealing with the combination of relatively high home prices and limited inventory. Recent reporting on the state's market describes demand as continuing to hold up even as mortgage rates have climbed.
Translation?
Buyers have less room for error.
Overpaying for a house that needs $75,000 in work doesn't feel quite as cute when you're also paying 7%+ interest.
2. Sellers Can't Ignore Affordability
This is where things get interesting.
Connecticut still has a serious inventory problem. Single-family homes for sale were down year-over-year in August, and available inventory remains historically low.
That gives sellers some protection.
But it doesn't give sellers a license to price their homes based on what they wish they were worth.
Higher mortgage rates mean buyers are paying closer attention to the entire cost of the purchase. A home that is overpriced may sit longer, require a price adjustment, or lose buyers to a property that offers better value.
The days of "let's just put it high and see what happens" are getting more expensive.
In a higher-rate environment, strategic pricing matters even more.
3. Fall Could Bring Fewer Buyers—But Also Less Competition
Here's the silver lining for buyers.
Higher rates can discourage some would-be buyers from entering the market. Mortgage applications declined 1.5% for the week ending September 18, according to the Mortgage Bankers Association.
That doesn't mean buyers disappear.
It means some buyers may decide to wait.
For the buyers who remain active, that could mean fewer bidding wars and a little more negotiating room on certain properties.
And because Connecticut's inventory remains tight, we are unlikely to see every property suddenly turn into a buyer's market.
In fact, recent Connecticut market reporting indicates that inventory remains historically low despite some improvement in listings.
So don't expect a repeat of the frenzy of a few years ago—but don't expect sellers to start giving houses away, either.
4. The "I'll Just Wait for Rates to Drop" Strategy Has a Catch
This is one of the biggest conversations I expect to have with buyers this fall.
"Should I wait until mortgage rates come down?"
Maybe.
But here's the problem: there's no guarantee that waiting will make the overall purchase cheaper.
If rates eventually fall, more buyers who have been sitting on the sidelines could jump back into the market.
More buyers competing for limited inventory can put upward pressure on prices.
That's why the better question isn't necessarily:
"When will mortgage rates go down?"
It may be:
"Does buying this particular home make financial sense for me at today's rate?"
If the answer is yes, buying can still make sense.
And if rates eventually decline enough to make refinancing attractive, that's a conversation you can have later. But refinancing should never be assumed or treated as guaranteed.
5. Sellers With a Reason to Move May Have an Advantage
Higher rates have created what economists and real estate professionals often call a "lock-in" effect.
Homeowners who secured very low mortgage rates in previous years may be reluctant to give them up.
That means many homeowners who might otherwise sell are staying put.
Connecticut's limited inventory is partly tied to this dynamic, with homeowners reluctant to trade existing low-rate mortgages for today's significantly higher borrowing costs.
But life doesn't always cooperate with mortgage rates.
People still get new jobs.
Kids still go to college.
Families still grow.
Divorces still happen.
People still retire.
And sometimes you simply decide that you are done maintaining the house with the 1970s kitchen.
Those sellers may have an advantage because buyers still need homes—and there aren't enough of them.
6. Expect Buyers to Be More Strategic
Today's buyer is likely to look at a home differently than they did when borrowing costs were substantially lower.
They're going to think more carefully about:
- Monthly payment
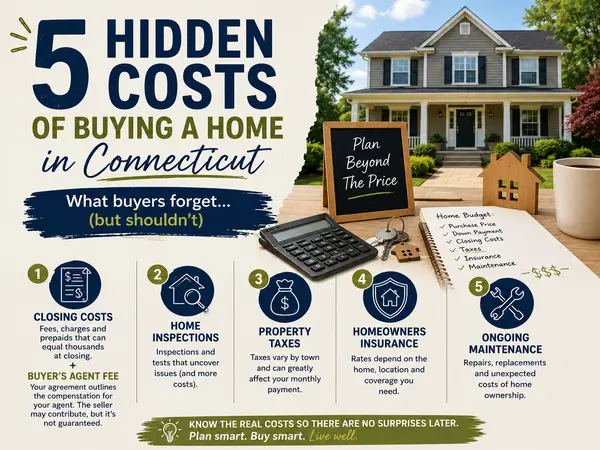
- Property taxes
- Homeowners insurance
- Maintenance costs
- Energy efficiency
- Renovation expenses
- HOA fees
- Resale potential
- Overall value
A pretty kitchen isn't enough if the roof is 25 years old and the taxes are enormous.
Buyers are doing more math.
And sellers need to understand that.
The home doesn't just have to look good. The numbers have to make sense.
7. Fall Is Still a Real Estate Season Worth Paying Attention To
Here's what I don't want homeowners to hear in all of the rate headlines:
"The market is dead."
It isn't.
Fall remains an active real estate season in Connecticut. While activity traditionally slows as the holidays approach, recent Connecticut market commentary indicates that fall has remained a vibrant period for real estate in recent years.
The market is simply operating under different conditions.
There are fewer easy transactions.
Buyers have to be more strategic.
Sellers have to be more realistic.
And pricing matters—a lot.
So, What Should You Do This Fall?
If you're a buyer:
Don't panic over the headline number.
Instead, talk with your lender about what today's rates mean for your actual monthly payment and purchasing power.
Then determine what you're comfortable spending—not simply what the bank says you qualify for.
And don't assume that waiting automatically means you'll get a better deal.
If you're a seller:
This is not the fall to test the market with an unrealistic price.
Your home needs to be positioned correctly from day one.
That means looking at current comparable sales, competing inventory, condition, presentation, and what today's buyers can realistically afford.
Because when buyers are paying 7%+ interest, overpricing becomes even harder to overcome.
The Bottom Line
The recent increase in interest rates is another headwind for the Connecticut housing market—but it isn't necessarily a reason to sit out the fall.
Connecticut still has limited inventory, buyers who need to move, and sellers who have compelling reasons to sell.
What has changed is the margin for error.
Buyers need to understand the numbers. Sellers need to understand the market. And both need a strategy that reflects the reality of 2026—not the real estate market of five years ago.
If you're thinking about buying or selling in Connecticut this fall, let's talk about what the current market actually means for your situation—not what the latest scary mortgage-rate headline says.
Smart moves start here.
Categories
Recent Posts