National Prices Just Fell for the First Time in 3 Years. Newtown Didn't Get the Memo.
DIRECT ANSWER: National home prices just fell year over year for the first time in more than three years — the median U.S. sale price is $389,601, down 0.1%. In Newtown, that headline doesn't apply: homes sell at roughly asking price, the median sits near $670,000, and Connecticut is a seller's market. The national story is real. It's not your story.
If you scrolled past a headline this week that said home prices are finally falling, you weren't imagining it — and you weren't wrong to wonder what it means for you. The national numbers are real, and they're the first of their kind in more than three years. But here's the thing nobody puts in the headline: the United States is not one housing market. It's thousands of them, and Newtown is not the one that's falling.
So let's do what the headlines won't — put the national number next to the local ones, and see which market you're actually standing in.
What actually happened nationally?
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
Redfin's weekly report, published October 29, 2026, put the median U.S. home-sale price at $389,601 for the four weeks ending October 25 — down 0.1% from a year earlier. That's the second straight weekly decline (the week before was down 0.2%), and the first annual decline in more than three years.
The rest of the national picture is just as soft:
- Pending sales hit a record low — 276,352, down 15.9% from a year ago, the lowest in Redfin's records going back to 2021, with declines in all 50 of the largest metros for a third straight week.
- The typical monthly payment is $2,786 at a 7.32% mortgage rate — up 10.7% from a year ago and the second-highest on record. That's the real story behind the price dip: buyers aren't getting deals, they're getting priced out of the payment.
- New listings fell to their lowest since January — 352,421, down 4% year over year. Sellers are pulling back too.
- Sellers outnumber buyers by roughly 63% nationally, the widest gap since 2013.
Now, straight talk cuts both ways, so here's the honesty check the headlines skip: this is a 0.1% dip in one rolling four-week measure, not a crash. The National Association of Realtors' monthly median for existing homes was $417,500 in September — still up 1.3% from a year earlier, its 39th straight month of annual gains. The two measures count different things, so they don't always agree. What they agree on is that nationally, the market has lost its momentum. Prices aren't plunging. They've just stopped climbing — for the first time in three years.
KEY TAKEAWAY: Nationally, prices inched down 0.1% — the first annual decline in 3+ years — while pending sales hit a record low. Real, but small. Not a crash. A stall.
The numbers, side by side
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
Same month. Four different markets:
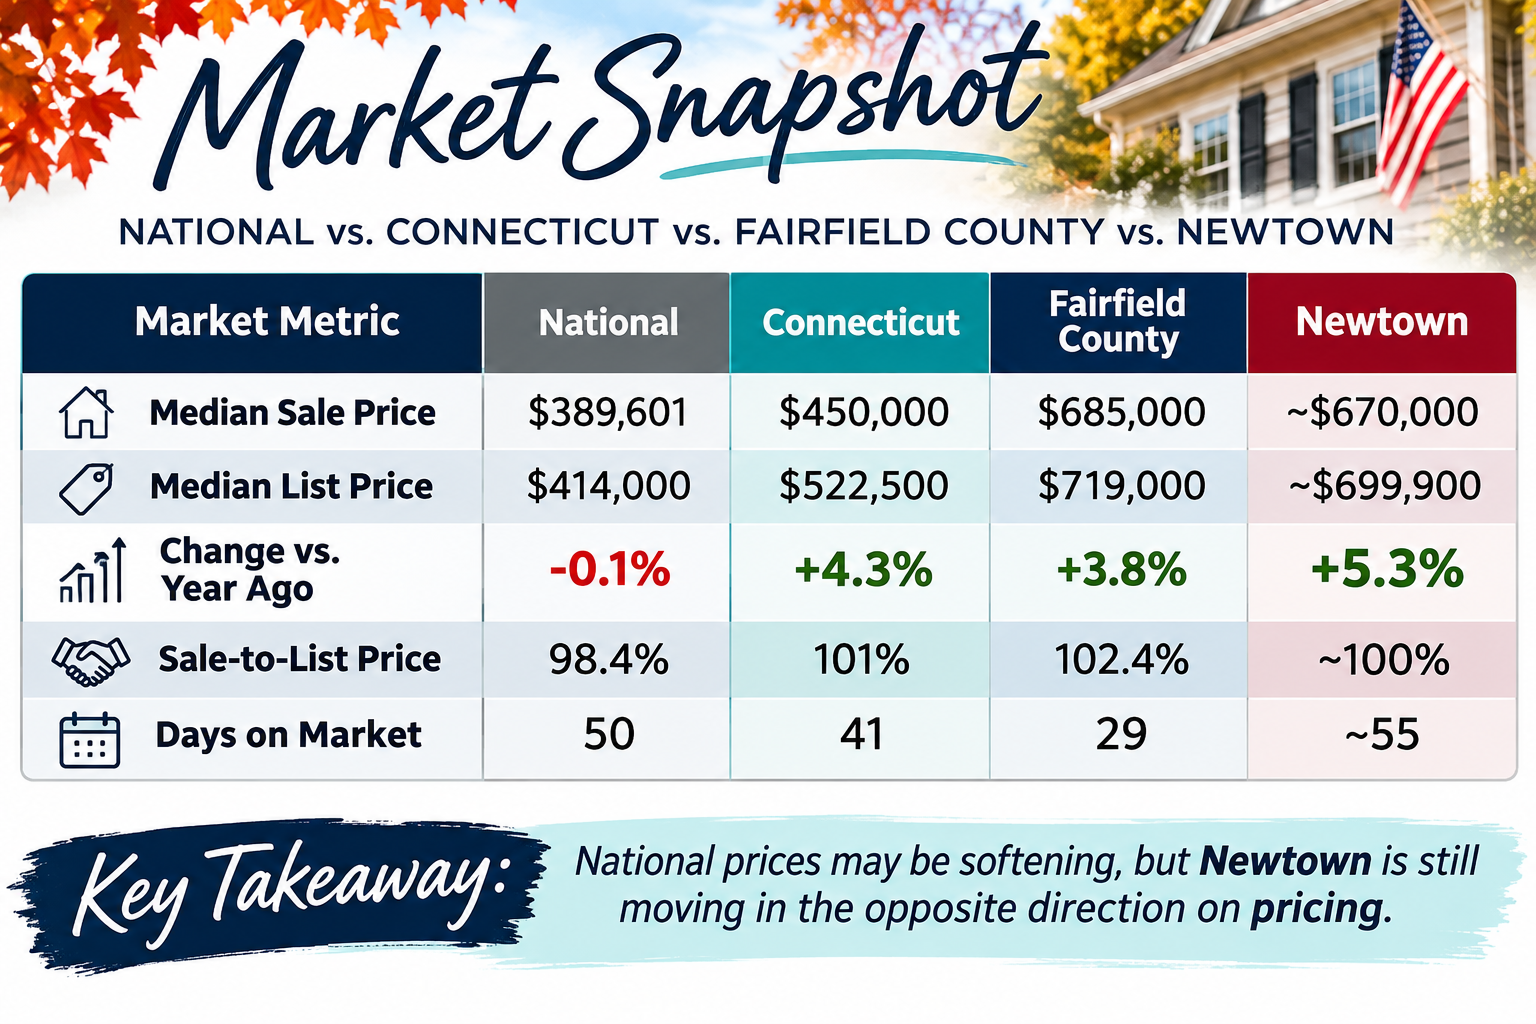 All figures October 2026. National: Redfin, four weeks ending Oct 25, 2026. Connecticut: Realtor.com, Oct 2026; change vs. a year ago from Redfin. Fairfield County: SmartMLS October 2026 Market Snapshot (median sale price $685,000, +3.8% year over year, median 29 days on market); median list price from the Connecticut weekly MLS pulse, week ending Oct 16, 2026; sale-to-list 102.4% from SmartMLS, last 90 days through Oct 26, 2026. Newtown: RealtyTrac, Oct 2026; days on market and sale-to-list from recent MLS-derived market data. Figures move — verify before making decisions.
Read the numbers the way a buyer should: national is the only one pointing down. Connecticut's median sold price is up 4.3% from a year ago, homes sell at 101% of asking in 41 days, and the state is still classed a seller's market. Fairfield County's median sale price is $685,000 — up 3.8% from a year ago — selling at 102.4% of asking in a median 29 days. And Newtown's median sale price sits near $670,000 — up about 5% from a year ago — selling at roughly asking price in about 55 days.
That's not a town that got the memo. That's a town that never received it.
KEY TAKEAWAY: Screenshot the numbers. National down 0.1%, Connecticut up 4.3%, Fairfield County up 3.8%, Newtown up about 5% — same month, opposite directions.
Why didn't Newtown get the memo?
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
Because the forces dragging national prices down barely exist here — and the forces holding prices up are doing overtime.
Supply is still thin where it matters. Nationally, sellers outnumber buyers and listings are piling up. In Connecticut, homes clear in 41 days at 101% of asking. Fairfield County's median list is $719,000, and in Fairfield itself, sales were recently averaging 105% of asking. When the good stuff is scarce, the good stuff doesn't discount.
The Northeast fell the least. When pending sales dropped nationally, the Northeast dropped least of any region. The national "buyer's market" is mostly a Sun Belt and Mountain West story — places where builders overbuilt and investors are retreating. Fairfield County never had that glut.
The payment problem cuts both ways. At 7.18%, the rate is the same everywhere — and it's the reason national demand is frozen. But in Newtown, the buyers who are still in the market are the ones who can carry the payment, and they're competing for a thin pool of homes. A $670,000 Newtown home with 20% down runs about $3,631 a month in principal and interest at 7.18% — serious money, but the buyers writing offers here have already done that math and decided the house is worth it. Thin demand plus thin supply equals a balanced market, not a falling one.
And the Fairfield County arbitrage is still real. You're in the same county as Greenwich and Westport without Greenwich and Westport prices. A comparable house 30 minutes south costs hundreds of thousands more. Newtown is where smart Fairfield County buyers figured out the value — and that math doesn't change because a national median ticked down a tenth of a percent.
KEY TAKEAWAY: Newtown isn't defying gravity. It's just a different market — thin supply, steady demand, and a value story the national numbers can't see.
So should Newtown buyers wait for prices to fall here?
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
No — not on the strength of this headline, anyway.
A 0.1% national dip is not a local price cut, and waiting for a national trend to arrive in Newtown means waiting in a market where homes still sell at asking in under two months. While you wait, the inventory stays thin, the rate stays above 7%, and the house you actually want can still sell to someone else. The buyers winning in Newtown right now aren't the ones timing a national dip. They're the ones who know their numbers and move when the right house hits. I went deep on the rate side of this exact question last week — whether Newtown buyers should wait for rates to drop — and the answer there is the same: the rate isn't coming to rescue you, so the decision is the payment, not the headline.
The honest reason to wait has nothing to do with this headline: if the payment doesn't fit your budget today, wait until your finances — not the Fed, not Redfin — say go. A trusted local mortgage lender can run your real numbers and tell you plainly what works. I won't run your financing numbers for you; that's the lender's job, and they do it properly.
Here's what that looks like from the buyer's side:
“As a first time homebuyer she made the process so easy and smooth from start to finish. Trish also sent weekly updates by email with progress and next steps which took the stress out of the home buying process!”— Simone Ross, first-time buyer, Danbury, CT — five stars on Zillow, October 2026
KEY TAKEAWAY: Waiting for a 0.1% national dip to become a Newtown price cut is waiting for a train that isn't coming to this station.
And sellers — should you cut your price because the headlines say prices are falling?
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
Also no — not because a national median moved.
Nationally, a record 22% of listings have already cut their prices — and even so, the national sale-to-list ratio held near 98%. Cuts are common; fire sales are not. In Connecticut, where homes sell at 101% of asking, cutting your price to match a national headline is pricing to someone else's market. You're not competing with the national median. You're competing with the other Newtown listings this month, and there aren't many of them.
What actually moves a Newtown home right now is pricing to the local buyer pool and the local payment. At 7.18%, a seller concession aimed at the buyer's rate — a buydown or closing-cost credit — can move the monthly payment more than the same dollars off the price. Ask your agent and your lender which lever does more for your specific house, because the answer isn't the same for every listing. That's the payment math in action — what buying a Newtown home actually costs, line by line — and it's why I keep telling sellers to price the payment, not the sticker.
And if your home is sitting: the problem usually isn't the national headline. It's the price relative to the three most recent comparable sales on your street, the condition buyers see on the walkthrough, or a payment that doesn't pencil at today's rate. Fix the thing that's actually wrong, not the thing the news is shouting about. And if it's sitting through the cold months, how to prep a Connecticut home for a winter sale covers the condition and presentation fixes that actually move a listing in this season.
KEY TAKEAWAY: Price to the Newtown buyer pool, not the national headline. Your competition is the house down the street, not the U.S. median.
What to watch instead of the national headline
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
If you want to know where Newtown is actually headed, stop refreshing the national median and watch these four local signals instead:
- Newtown days on market. Around 55 days right now. If that number climbs toward 70 or 80 and stays there, the market is genuinely cooling. A single month doesn't count — watch the trend.
- Newtown sale-to-list. Roughly 100% today. If winning offers start landing at 95% or below, sellers are losing leverage. Until then, they're not.
- New listings in Newtown. New listings nationally just hit their lowest since January. If Newtown listings surge while buyers stay thin, that's the first real sign of a local shift. So far, the opposite is happening.
- The rate. Everything in this market still runs through the 30-year fixed — 7.18% as of the November 5 Freddie Mac survey — down from 7.24%, the third straight weekly decline, with forecasts keeping it above 7% through 2027. A meaningful rate drop would bring buyers back faster than any price dip ever could.
KEY TAKEAWAY: The national median is a weather report for somewhere else. Days on market, sale-to-list, local listings, and the rate are the forecast for your street.
What should you do this week instead?
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
- Buyers: get your real numbers from a trusted local mortgage lender. Not an online calculator — a Loan Estimate on your actual situation. At 7.18%, the payment is the whole ballgame, and only your lender can tell you what yours actually is.
- Tour the Newtown homes in your range now. See what ~$670,000 actually buys this month, and watch how fast the good ones move. That's your market research — better than any headline.
- Sellers: price to your last three comparable sales, not to the news. And ask whether a rate buydown or closing-cost credit would do more for your buyer than a price cut. The payment is what buyers feel; price the payment.
- Everyone: ignore the national median until it shows up locally. If Newtown's days on market and sale-to-list start moving, I'll be the first to tell you. They haven't yet.
KEY TAKEAWAY: The buyers and sellers winning in Newtown right now aren't reacting to national headlines. They're reading the local numbers and moving on them.
The receipts behind the straight talk
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
I'm not guessing about Newtown. Between 2018 and 2026 I closed 122 Connecticut transactions totaling roughly $45 million (SmartMLS) — and I'm licensed in Connecticut, New York, and Tennessee. I live and work in Newtown. This is my market, not a market I read about.
Smart Moves Start Here
Thinking about buying or selling in Newtown, Fairfield County, or anywhere in Connecticut? Let's talk strategy — which neighborhoods fit, what to watch for, and how to move fast when the right house hits. And I'll connect you with a trusted local mortgage lender who'll run your real financing numbers, so you know exactly what you can do before you fall in love with a house. No pressure, no sales pitch. Just straight talk.
Tricia Farin, Realtor® · 203-470-8250 · triciafarinrealtor.com
Real Broker CT, LLC · 855-450-0442
Sources: Redfin housing market update, Oct 29, 2026 (four weeks ending Oct 25, 2026 — median sale price $389,601, −0.1% YoY; pending sales 276,352, −15.9% YoY; typical monthly payment $2,786 at 7.32%; new listings 352,421; 4.5 months' supply; median 50 days on market; sellers outnumber buyers ~63%); National Association of Realtors, Sept 2026 (monthly median existing-home price $417,500, +1.3% YoY); Realtor.com, Oct 2026 (Connecticut median listing $522,500, median sold $450,000, 41 days on market, sale-to-list 101%); Connecticut weekly MLS pulse, week ending Oct 16, 2026 (Fairfield County median list $719,000); SmartMLS October 2026 Market Snapshot (Fairfield County median sale price $685,000, +3.8% YoY, median 29 days on market; sale-to-list 102.4%, last 90 days through Oct 26, 2026); RealtyTrac, Oct 2026 (Newtown median sold $687,400, +5.3% YoY; median list $699,900); Freddie Mac Primary Mortgage Market Survey, week ending Nov 5, 2026 (30-yr fixed 7.18%; 15-yr 6.57%); Newtown median ~$670,000, ~55 days on market, ~100% sale-to-list from recent MLS-derived market data. Figures move — verify before making decisions. Payment figures are illustrative principal-and-interest calculations on a 30-year fixed loan, not a financing offer.
Categories
Recent Posts