What Does It Actually Cost to Buy a Home in Newtown, CT Right Now?
Direct answer: Buying in Newtown is absolutely doable — most single-family homes sell in the $550K–$800K range, and with 80+ active listings right now you've got more choices than buyers have had in years. Condos here are mostly 55+ communities starting around $450K. Plan on roughly $65K–$130K cash to close on a typical $650K purchase, plus a few costs most calculators conveniently forget to mention (including your agent's fee — more on that below). All-in monthly: around $4,700. Here's the unfiltered version.
Let's clear something up: Newtown is not some unattainable Fairfield County fantasy. It's the part of Fairfield County where your money still behaves itself — top-rated schools, an actual town center with character, parks, lakes, and homes that don't require selling a kidney. The buyers who "can't afford Newtown" usually just haven't run the real numbers. So let's run them.
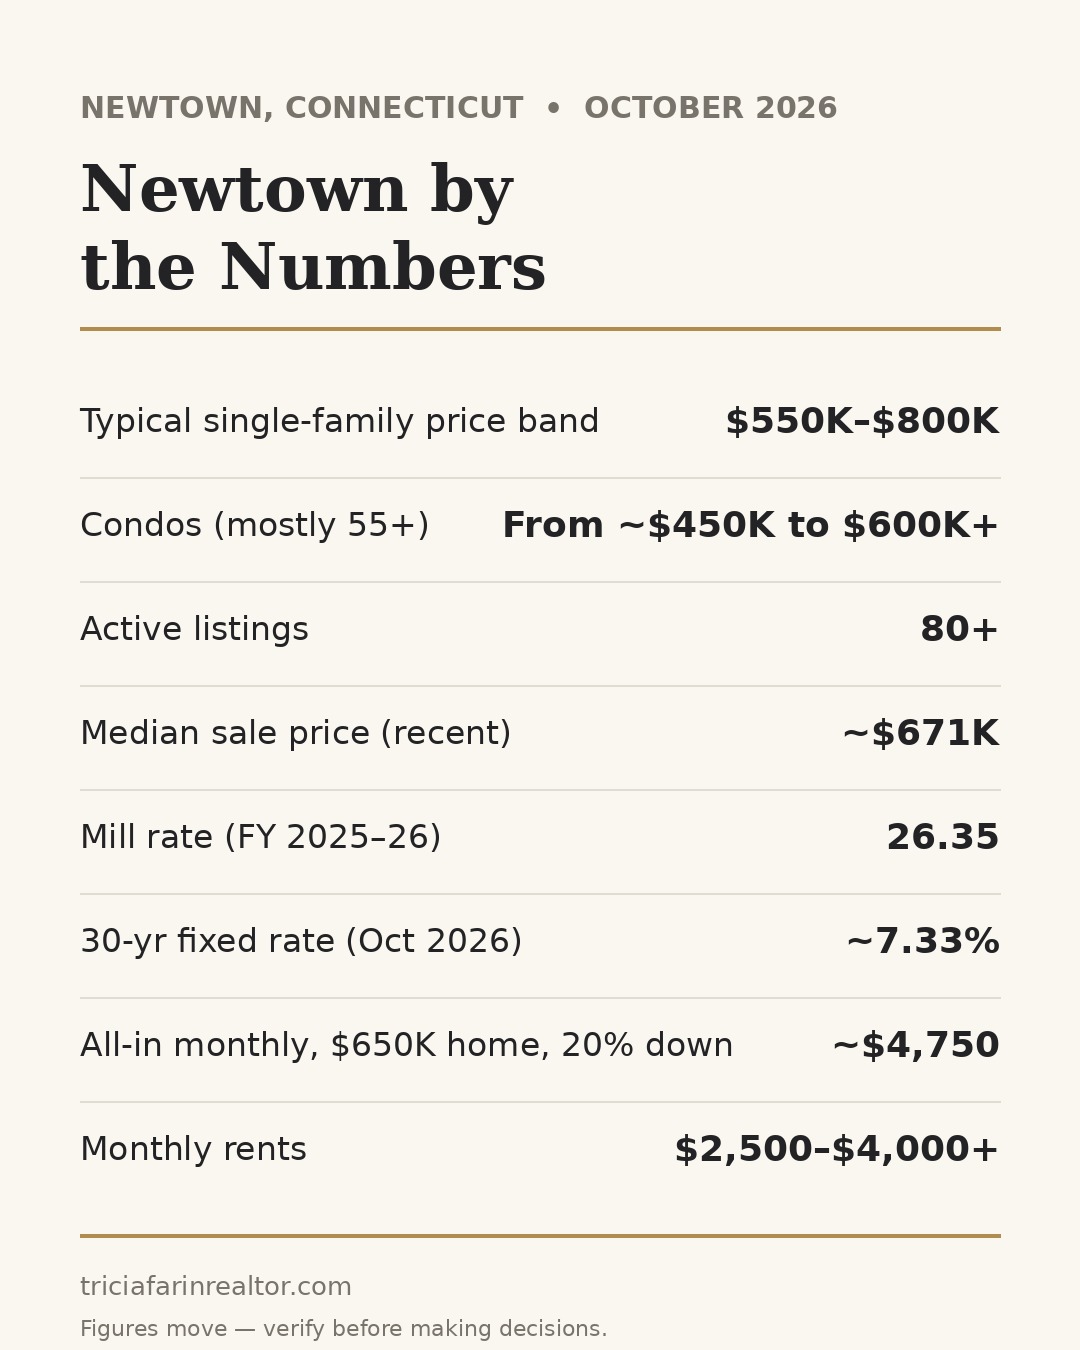
Sources: MLS and county-record data; Freddie Mac rates; Town of Newtown. Figures move — verify before making decisions.
Key takeaway: Screenshot the table, skip the doom-scrolling. This is the whole picture on one screen.
Why Newtown, though? The part Zillow won't tell you
Numbers aside, here's why people actually land here and stay: Newtown's schools are consistently among the best in the state — that's the headline driver for half my buyers. You've got a genuine Main Street, not a strip mall with aspirations. Sandy Hook village, Dickinson Park, Lake Lillinonah and Lake Zoar ten minutes away, and a community that still does things like the Labor Day parade without irony.
And the value proposition is real: you're in Fairfield County — same county as Greenwich and Westport — without Greenwich and Westport prices. A comparable house 30 minutes south costs you $300K more and hands you a higher tax bill for the privilege. Newtown is where smart Fairfield County buyers figured out the arbitrage.
Yes, there's no Metro-North stop. That's not a flaw, that's the discount. Drive the commute once at rush hour, decide if the trade works for you, and move on.
Key takeaway: People don't buy in Newtown because it's cheap. They buy because it's the best value in Fairfield County and the town actually delivers on the lifestyle.
The monthly payment, no fairy dust
On a typical $650,000 Newtown home with 20% down ($130,000): roughly $3,575 in principal and interest at today's ~7.33%, about $1,000 in property taxes (26.35 mill rate on 70%-assessed value), ~$175 insurance. Total: ~$4,750/month.
With 10% down, add mortgage insurance and you're just past $5,000. My rule: keep the total payment at or under 28% of gross monthly income. On $4,750, that's a household income around $200K — squarely in the range of the families buying here every week.
Perspective check: renting a comparable place runs $2,500 to $4,000+/month — cheaper than owning today, sure, but it builds exactly zero equity and your landlord can raise it whenever the mood strikes. Owning locks your cost and pays you back.
Key takeaway: $4,750 a month sounds like a lot until you realize it's buying an asset in a top-school town instead of funding someone else's retirement.
Cash to close: the part calculators hide
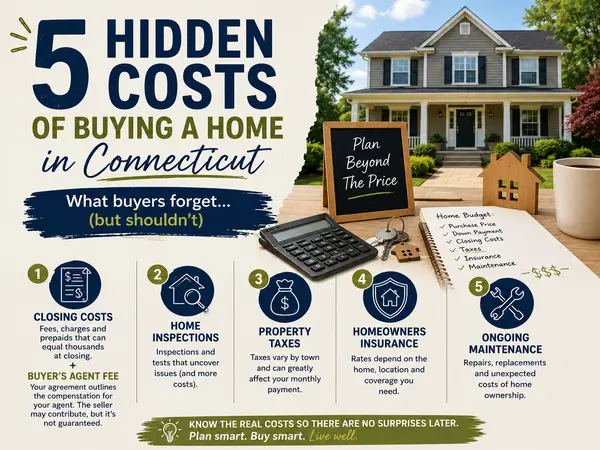
Here's where I get snarky, because those online "how much house can I afford" calculators are lying to you by omission. On a $650K purchase, you need:
- Down payment: 3% ($19,500) to 20% ($130,000)
- Closing costs: 2–5% ($13,000–$32,500) — attorney, appraisal, title, prepaids
- Buyer agent compensation: since the 2024 industry changes, you sign an agreement spelling out your agent's fee up front. Often the seller still covers it via concession, but if not, it can come out of your pocket — budget for the possibility instead of being surprised at the closing table
- Moving + first fixes + cash cushion: $5,000–$10,000 minimum
Realistic totals on $650K:
- 10% down buyer: ~$65,000 down + ~$20,000 closing + fee contingency = ~$85,000–$95,000 cash
- 20% down buyer: ~$130,000 down + ~$20,000 closing = ~$150,000 cash
Connecticut's conveyance tax is the seller's problem, so at least someone else is suffering at that table.
Key takeaway: The down payment is maybe two-thirds of what you'll actually spend. Anyone who told you "just save 20%" did you dirty — it's 20% plus everything above.
Four local things worth knowing (none of them scary)
- Septic and wells are normal here. You'll pay a few hundred extra for a septic inspection during due diligence — that's it. After that it's pumping every few years and forgetting about it. Manageable, not menacing.
- Ask about heat. Most Newtown homes run on oil — natural gas just isn't readily available throughout town, and some homes have converted to propane. Get the seller's fuel bills so you can budget honestly.
- A revaluation is happening right now. Connecticut law requires towns to revalue every five years, and Newtown's revaluation is for the October 1, 2026 grand list — notices are going out now. If you buy this fall, know the assessment (and your tax bill) could shift; formal appeals to the Board of Assessment Appeals are due by February 20, 2027. The next revaluation after this one: October 2031.
- You're 30 minutes from the Gold Coast premium. That distance is literally why you can afford the house. Own the trade-off.
Key takeaway: Every town has quirks. Newtown's quirks are a $500 inspection and a commute you test-drive once. Meanwhile you're pocketing hundreds of thousands versus buying south.
So — can you actually do this?
With 80+ homes to choose from, sellers negotiating like it's a normal market again, and the math laid out above, the buyers winning in Newtown right now aren't the richest ones — they're the ones who know their numbers and pounce when the right house hits. Be that buyer.
Smart Moves Start Here
Thinking about buying in Newtown, Fairfield County, or anywhere in Connecticut? Let's talk strategy — which neighborhoods fit, what to watch for, and how to move fast when the right house hits. And I'll connect you with a trusted local mortgage lender who'll run your real financing numbers, so you know exactly what you can do before you fall in love with a house. No pressure, no sales pitch. Just straight talk.
Categories
Recent Posts